Sumitomo Forestry Adds Lower-Cost Karusuke Cargo Drone for Forestry Work
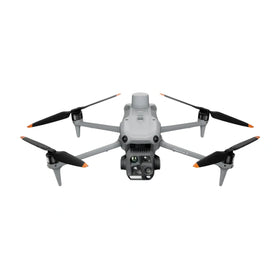
Sumitomo Forestry is expanding its forestry cargo drone lineup with the Mazex Karusuke series, offering a smaller and more affordable airframe that matches the payload of the earlier Morito 25. The move signals growing price competition in Japan's industrial cargo drone segment.

Quick answer
Sumitomo Forestry is introducing the Mazex Karusuke series to forestry operators through its own network, with the Karusuke 25 matching the payload of the earlier Morito 25 at a lower price and in a smaller airframe.
- The Karusuke 25 matches the Morito 25 payload in a smaller, lower-cost airframe
- Sumitomo Forestry will distribute the series through its own forestry operator network
- The announcement was made in collaboration with JUIDA, the Japan UAS Industrial Development Association
- The move points to intensifying price competition in industrial cargo drones
Evidence: DRONELIFE · FAA UAS official guidance
Market context
Turn market news into a buy, repair, or trade-in decision.
Compare pre-owned availability, resale timing, and repair economics before the market moves again.

Verified facts
What the available evidence confirms
| Model | Payload | Price Position | Airframe Size |
|---|---|---|---|
| Karusuke 25 | Matches Morito 25 | Lower | Smaller |
| Morito 25 | Reference payload | Higher | Larger |
Sumitomo Forestry is expanding its forestry cargo drone offering with the Mazex Karusuke series, a lower-cost airframe line that the company plans to distribute through its own network of forestry operators. The announcement, reported by DRONELIFE in collaboration with JUIDA, the Japan UAS Industrial Development Association, marks a notable step in the commercialization of cargo drones for timber logistics and remote forest operations.
The central development is straightforward: the Karusuke 25 matches the payload capacity of the earlier Morito 25, but does so in a smaller airframe and at a lower price point. For forestry operators who have been watching cargo drone economics from the sidelines, that combination of reduced cost and reduced physical footprint could lower the barrier to adoption in an industry where margins are tight and terrain is unforgiving.
What the Karusuke series changes in forestry cargo drone economics
According to the DRONELIFE report, Sumitomo Forestry will introduce the Mazex Karusuke series to forestry operators through its own distribution network. The Karusuke 25 is positioned as a direct response to the cost and size constraints that have limited uptake of the earlier Morito 25. By matching payload while shrinking the airframe and reducing price, the new series targets a practical procurement problem: operators who need reliable lift capacity but cannot justify the capital outlay or logistical burden of a larger platform.
This is a meaningful signal for the broader industrial drone market. Cargo drones have historically faced a difficult value proposition in forestry, where payloads are heavy, flight distances are short but steep, and operating budgets are constrained. A smaller, cheaper airframe that preserves the same lift capability changes the procurement calculus. It suggests that drone makers are now competing on total cost of ownership rather than raw performance alone, a shift that typically precedes wider fleet adoption.
Reboot Hub analysis: the Karusuke announcement is less about a single model and more about the direction of industrial drone pricing. When a major forestry company with Sumitomo Forestry's reach begins distributing a lower-cost alternative through its own channels, it effectively validates the idea that cargo drones are becoming procurement items rather than pilot projects.
Distribution through Sumitomo Forestry's operator network
The DRONELIFE report indicates that Sumitomo Forestry will use its own network to bring the Karusuke series to forestry operators. That distribution approach matters because it bypasses the generic drone reseller channel and places the product directly in front of buyers who already have forestry-specific workflows, safety requirements, and terrain challenges. For a cargo drone, the credibility of the distribution channel can be as important as the airframe itself.
For fleet planners, this raises a practical question: does a forestry operator buy a cargo drone from a generalist drone dealer, or from a forestry company that understands timber logistics and can offer operational context? The Sumitomo Forestry approach suggests that industrial drone sales are becoming more verticalized, with domain-specific distribution networks carrying products that generalist channels may not support well.
The collaboration with JUIDA also matters. JUIDA's involvement signals that the announcement is positioned within Japan's broader industrial UAS ecosystem, where standards, training, and operator certification are coordinated through industry associations. For international observers, the JUIDA connection is a reminder that Japan's commercial drone market operates with its own institutional landscape, distinct from the FAA or EASA frameworks that dominate North American and European coverage.
What this means for drone owners and the market
The Karusuke series is a forestry-specific product, but its implications extend to how commercial drone buyers think about fleet economics. A lower-cost airframe that matches the payload of a more expensive predecessor is the kind of development that forces operators to revisit their procurement assumptions. If a smaller, cheaper platform can do the same lifting job, the residual value of older, larger cargo drones may come under pressure, and repair versus replace decisions become more complicated.
For owners of pre-owned DJI drones and enterprise fleets, the lesson is that industrial drone pricing is not static. When manufacturers introduce lower-cost models that preserve core performance, the secondary market adjusts. Fleet managers who overpaid for capacity that is now available in a smaller and cheaper form factor may find that their assets depreciate faster than expected. Buyers, by contrast, gain leverage: the existence of a lower-cost alternative strengthens the case for negotiating on used enterprise platforms. For operators evaluating repair versus replacement, resources like the Drone Wiki can help clarify platform-specific maintenance and parts considerations before committing to a new purchase. For owners evaluating service and lifecycle risk, Drone Wiki explains the relevant repair, parts, resale, or operational path.
The practical takeaway for a buyer or fleet manager is to evaluate cargo drones on payload-per-dollar and payload-per-kilogram rather than on brand or airframe size alone. The Karusuke 25's positioning suggests that the market is moving toward functional equivalence at lower price points, which means procurement teams should benchmark any new cargo drone against the cheapest platform that meets their lift requirement, not the most familiar one.
Broader signals for industrial drone supply chains
The Karusuke announcement also carries supply chain implications. A smaller airframe that matches the payload of a larger one typically means changes in motor configuration, battery sizing, or structural materials. For repair customers and spare parts buyers, that can translate into different maintenance profiles and parts availability. Operators who standardize on a single cargo drone platform should consider whether a lower-cost alternative will have comparable parts support, especially in remote forestry regions where downtime is expensive.
The involvement of Mazex as the industrial drone maker, with Sumitomo Forestry acting as the distribution and domain partner, reflects a broader pattern in commercial drone markets: hardware specialists building airframes, and domain companies bringing them to vertical buyers. That division of labor can accelerate adoption, but it also means that support quality may depend on the distribution partner as much as the manufacturer. Forestry operators evaluating the Karusuke series should ask how warranty, repair, and parts logistics will be handled through Sumitomo Forestry's network, not just what the airframe costs upfront.
For the pre-owned DJI market specifically, the Karusuke development is a reminder that enterprise drone value is tied to the pace of new product introductions. When lower-cost alternatives appear in adjacent industrial segments, they can influence buyer expectations across the broader commercial drone category. A forestry operator who sees a smaller, cheaper cargo drone enter the market may become more price-sensitive when evaluating used DJI Matrice or other enterprise platforms for non-forestry tasks. The direction of travel is clear: commercial drone buyers are gaining more options at lower price points, and that trend rewards patience and careful benchmarking.
FAQ
Frequently asked questions
What is the Karusuke 25 and how does it compare to the Morito 25?
The Karusuke 25 is a cargo drone in the Mazex Karusuke series that Sumitomo Forestry will distribute to forestry operators. According to the DRONELIFE report, it matches the payload of the earlier Morito 25 while using a smaller airframe and a lower price point.
Who is distributing the Karusuke series to forestry operators?
Sumitomo Forestry will introduce the Mazex Karusuke series through its own network of forestry operators. The announcement was made in collaboration with JUIDA, the Japan UAS Industrial Development Association.
What should a drone buyer or fleet manager take away from this announcement?
Buyers should benchmark cargo drones on payload-per-dollar rather than brand or airframe size. The arrival of a lower-cost platform that matches an existing payload capacity suggests that industrial drone pricing is becoming more competitive, which may affect procurement timing, repair-versus-replace decisions, and the residual value of older enterprise platforms.
Which sources support this update?
The visible evidence links identify DRONELIFE and FAA UAS official guidance; each source is used only for the claim it directly supports.
What remains subject to change?
Retail pricing, availability, product bundles and regulatory timelines can change. Readers should verify the latest terms with the named retailer, manufacturer or regulator before acting.
How should buyers or operators use this analysis?
Use the verified facts as a starting point, then compare mission fit, lifecycle support, maintenance needs and current procurement terms before making a purchase or fleet decision.
Fonti consultate
- DRONELIFE - primary source
- FAA UAS official guidance - official regulator source
Reboot Hub Editorial fornisce analisi sugli acquisti, le riparazioni, la rivendita e l'operatività per i proprietari di droni. In caso di errori, contattateci per una revisione della correzione in conformità con la nostra politica editoriale.