China's Agricultural Drones Reshape Global Commercial UAV Demand
China's agricultural drone sector is emerging as a flagship for the country's intelligent manufacturing push, according to a Sina Finance report. The development signals shifting global demand patterns that commercial operators, fleet buyers, and pre-owned DJI market participants should monitor closely.

Quick answer
A Sina Finance report indicates that agricultural drones are becoming a new calling card for China's intelligent manufacturing sector, signaling broader commercial momentum for Chinese UAV producers in global markets.
- Sina Finance reports agricultural drones now represent a flagship category for China's intelligent manufacturing exports
- The development points to expanding production scale and potential supply chain maturation for Chinese commercial UAV makers
- Commercial operators should watch for pricing, parts availability, and service network shifts as agricultural drone volumes grow
- The pre-owned DJI market may see indirect effects if agricultural demand influences overall UAV component and production priorities
China's agricultural drone industry has moved from a niche farming tool to a recognized symbol of the country's broader intelligent manufacturing ambitions. According to a Sina Finance report, agricultural drones are now being positioned as a new calling card for Chinese industrial capability, a development that carries implications far beyond crop spraying.
Market context
Turn market news into a buy, repair, or trade-in decision.
Compare pre-owned availability, resale timing, and repair economics before the market moves again.

The report frames the sector's rise within China's ongoing push to export higher-value technology products rather than low-cost commodity goods. Agricultural drones sit at the intersection of autonomy, precision spraying, battery technology, and sensor integration, making them a natural showcase for the country's manufacturing evolution. For commercial UAV operators and buyers outside China, the signal is worth reading carefully: the same production ecosystems that build agricultural platforms increasingly shape pricing, component availability, and innovation cycles across the broader drone market.
The commercial significance of the agricultural drone shift
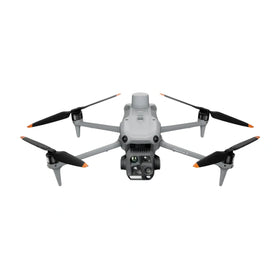
Sina Finance's characterization of agricultural drones as a calling card for intelligent manufacturing reflects a deliberate industrial strategy. Agricultural UAVs require rugged airframes, reliable autonomous flight control, precision liquid delivery systems, and increasingly sophisticated obstacle sensing. A sector that can produce these systems at scale demonstrates capabilities that transfer directly to other commercial drone categories, including inspection, mapping, and logistics platforms.
The practical implication for fleet managers is that component supply chains serving agricultural UAV production may increasingly overlap with those supporting other commercial airframes. Batteries, motors, electronic speed controllers, and flight controller components are shared across categories. When agricultural production volumes rise, suppliers gain economies of scale that can stabilize pricing and improve availability for adjacent product lines. Reboot Hub analysis suggests that operators planning multi-year fleet investments should treat agricultural drone growth as a leading indicator for broader component ecosystem health rather than an isolated farming niche.
What this means for drone owners and the market
For individual drone owners and small commercial operators, the agricultural drone story matters primarily through its effect on the wider UAV supply chain. A robust agricultural manufacturing base in China supports dense supplier networks, competitive component pricing, and faster iteration on core technologies like battery density and autonomous flight software. These improvements tend to flow into consumer and enterprise platforms over time, even when the immediate product categories differ.
The pre-owned DJI market is not directly tied to agricultural drone sales, but it is connected through shared manufacturing priorities and component demand. When Chinese UAV producers allocate production capacity toward high-volume agricultural platforms, the availability of certain components for other product lines can shift. Buyers evaluating inspected pre-owned DJI drones or genuine OEM spare parts should monitor whether agricultural demand creates bottlenecks or, conversely, drives down costs for common components. Reboot Hub analysis suggests that the current trajectory points toward broader component availability rather than scarcity, but procurement timelines may still shift as manufacturers balance product mix. Readers tracking these dynamics can reference the Drone Wiki for background on how commercial UAV supply chains and repair ecosystems interact. For owners evaluating service and lifecycle risk, Drone Wiki explains the relevant repair, parts, resale, or operational path.
Fleet operators should also consider the service and support implications. As Chinese agricultural drone manufacturers expand internationally, they typically build distributor networks, training programs, and spare parts channels. These investments can improve the overall repair infrastructure available to commercial operators in regions where such services were previously thin. A buyer or fleet manager should track which manufacturers are expanding service coverage in their operating region, since improved parts logistics for one UAV category often benefits adjacent categories through shared distribution infrastructure.
Regional market dynamics and export momentum
The Sina Finance report highlights a broader trend: Chinese technology exports are increasingly defined by complete systems rather than components. Agricultural drones embody this shift because they combine hardware, software, and operational workflows into a single exportable product. For international buyers, this means the competitive landscape for commercial UAV procurement is expanding beyond established Western brands to include Chinese platforms that may offer different price-performance tradeoffs.
Operators evaluating new equipment should weigh this competitive pressure carefully. Increased competition in the commercial UAV segment can drive down acquisition costs and accelerate feature development, but it also introduces questions about long-term support, firmware update cadence, and spare parts availability in specific regions. A prudent fleet manager will assess not just the purchase price of an agricultural or inspection platform, but the maturity of the manufacturer's regional service network and the accessibility of replacement components over a three-to-five-year operating horizon.
The agricultural drone sector's rise also has implications for regulatory perception. As more countries adopt agricultural UAVs for crop management, regulators gain operational data that can inform broader commercial drone frameworks. This gradual normalization of beyond-visual-line-of-sight operations in agricultural settings may eventually ease pathways for other commercial applications, though Reboot Hub analysis emphasizes that regulatory timelines remain uncertain and vary significantly by jurisdiction.
Supply chain and resale considerations for operators
The growth of China's agricultural drone manufacturing base introduces both opportunities and risks for commercial UAV buyers. On the opportunity side, higher production volumes across shared component categories can improve parts availability and reduce costs for maintenance and repair. On the risk side, rapid product iteration in agricultural platforms may accelerate obsolescence cycles for certain components, potentially affecting the long-term serviceability of older airframes.
For pre-owned DJI drone buyers, the key variable is how DJI and other major manufacturers allocate engineering and production resources in response to agricultural market growth. If agricultural platforms command a larger share of development attention, firmware and accessory support for older consumer and enterprise models could see slower refresh cycles. This does not suggest imminent obsolescence, but it does reinforce the value of purchasing pre-owned units through channels that verify condition, battery health, and firmware compatibility before sale.
Repair customers should also note that the expansion of agricultural UAV service networks may improve access to genuine OEM spare parts in regions that previously relied on slower import channels. As manufacturers build regional parts depots to support agricultural fleets, the same logistics infrastructure can serve other commercial and consumer repair needs. The practical takeaway is to monitor manufacturer service announcements and regional distributor expansions, since these often signal improved parts availability for multiple product lines simultaneously.
FAQ
Frequently asked questions
Why are agricultural drones being called a calling card for China's intelligent manufacturing?
According to the Sina Finance report, agricultural drones demonstrate China's ability to export complete, high-value technology systems that combine autonomy, precision hardware, and software. This positions the sector as a visible example of the country's shift toward advanced manufacturing rather than low-cost commodity production.
How does this affect commercial drone buyers outside China?
Commercial buyers may see indirect benefits through shared component supply chains, improved parts logistics, and increased competitive pressure on pricing. However, operators should evaluate each manufacturer's regional service network and spare parts availability before committing to new platforms.
Should pre-owned DJI drone buyers be concerned about agricultural drone growth?
Not directly. The pre-owned DJI market is connected to agricultural drone growth mainly through shared manufacturing priorities and component demand. Buyers should monitor whether agricultural production volumes affect component availability or firmware support cadence for older models, but the current trajectory suggests broader ecosystem health rather than scarcity.
Which sources support this update?
The article distinguishes reported information from analysis and does not present an unverified source as official confirmation.
What remains subject to change?
Retail pricing, availability, product bundles and regulatory timelines can change. Readers should verify the latest terms with the named retailer, manufacturer or regulator before acting.
How should buyers or operators use this analysis?
Use the verified facts as a starting point, then compare mission fit, lifecycle support, maintenance needs and current procurement terms before making a purchase or fleet decision.
Fonti consultate
- Source material - primary source
Al momento della pubblicazione non era disponibile ulteriore documentazione ufficiale.
Reboot Hub Editorial fornisce analisi sugli acquisti, le riparazioni, la rivendita e l'operatività per i proprietari di droni. In caso di errori, contattateci per una revisione della correzione in conformità con la nostra politica editoriale.